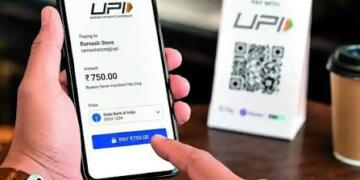



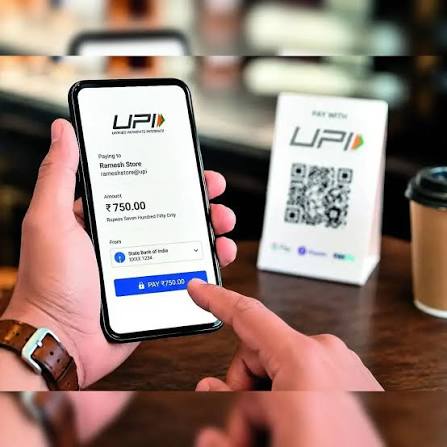
The Central Government has formally moved to keep small digital payments UPI Free, notifying that banks and payment system providers cannot impose direct or indirect charges on UPI transactions of up to ₹2,000. The move comes amid recent public discussion over whether changes to the Payment and Settlement Systems Act could eventually lead to charges on digital payments. The latest notification provides a clear statutory safeguard for millions of Indians who rely on UPI for everyday transactions.
The Ministry of Finance, through the Department of Financial Services, issued the notification on September 14 under Section 10A of the Payment and Settlement Systems Act, 2007. It specifically identifies UPI transactions up to ₹2,000 and RuPay-powered debit card payments as electronic modes for which banks and system providers cannot levy charges on either the person making or receiving the payment.
The notification is particularly significant because it uses the words “directly or indirectly”. This means financial institutions and payment providers cannot simply redesign a fee or introduce another mechanism to recover a transaction charge from users covered by the notification. For ordinary consumers, the immediate message is straightforward: small UPI payments remain UPI Free, providing certainty at a time when speculation about possible digital-payment fees had generated confusion.
The government’s decision also comes against the backdrop of amendments passed by Parliament earlier this year. The changes to the Payment and Settlement Systems Act removed the earlier statutory restriction and gave the Centre greater flexibility to specify electronic payment modes and determine how charges could be structured. This had prompted debate over whether the zero-charge framework for UPI could eventually be altered.
For millions of consumers, the importance of the latest notification lies in the sheer frequency with which small-value digital payments are made. From buying groceries and paying for meals to settling auto-rickshaw fares and sending money to local businesses, UPI has become embedded in everyday economic activity. Keeping these transactions UPI Free protects the convenience that helped digital payments spread rapidly across urban and rural India.
The government has also sought to distinguish between consumers and the broader question of merchant charges. Discussions around the Merchant Discount Rate, or MDR, have focused largely on the sustainability of the digital-payment ecosystem and the costs borne by banks, payment service providers and merchants. The latest notification, however, specifically protects UPI transactions up to ₹2,000 from charges being imposed on either side of the transaction.
The scale of India’s digital-payment revolution makes the policy significant. According to government data cited in recent reporting, the number of banks live on UPI increased from just 44 in financial year 2016-17 to more than 700 in 2025-26. Monthly transaction volumes crossed 2,300 crore in May 2026 and reached another record in July, demonstrating how deeply the platform has entered everyday commerce. The continued availability of UPI Free small-value payments therefore has implications far beyond convenience for individual consumers.
The notification also provides reassurance to small merchants who depend heavily on digital payments. Street vendors, neighbourhood shops, delivery workers and small service providers increasingly use QR codes as their primary payment channel. For transactions falling within the ₹2,000 ceiling, the government has now made clear that banks and system providers cannot impose charges on either the payer or recipient. The protection of UPI Free payments could consequently help preserve the low-friction nature of India’s digital marketplace.
At the same time, the notification does not amount to a blanket declaration that every UPI transaction of every value will remain permanently free of every possible merchant-side charge. The specific statutory protection notified by the Centre covers UPI transactions up to ₹2,000. Questions surrounding higher-value merchant transactions and the possible structure of MDR remain part of the wider policy discussion. This distinction is important because it prevents the latest decision from being misunderstood as a universal ban on every possible future payment-system fee.
For consumers, however, the immediate outcome is clear. Everyday payments within the notified ₹2,000 limit have received explicit protection, strengthening confidence in the system. The government’s decision to keep such transactions UPI Free also reinforces the role of digital payments as an accessible alternative to cash.
The development marks another important stage in India’s transformation into a digital-first economy. UPI has grown from a relatively new payment system into one of the country’s most widely used financial platforms. By providing statutory protection for small-value transactions, the Centre has sought to preserve the simplicity that made UPI popular while leaving room for policymakers to address the financial sustainability of the wider payments ecosystem. For ordinary Indians, the most important takeaway remains simple: for transactions covered by the notification, UPI Free is now backed by an explicit government order.